Why Opening New Accounts for Variety Rarely Helps a Credit Score
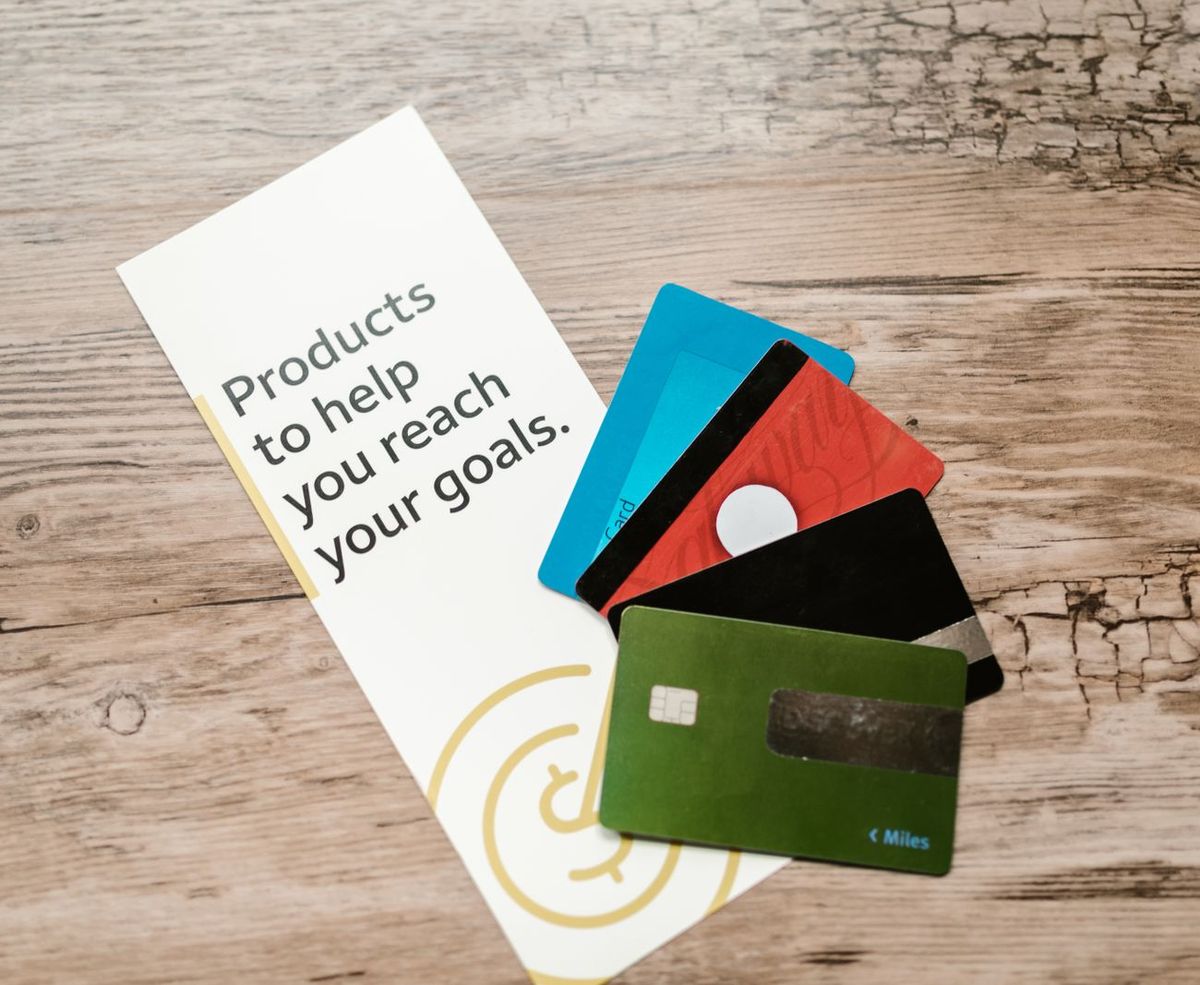
Credit scores reward borrowers who handle different types of credit responsibly, and that idea leads some people to a tempting shortcut. If variety helps, why not open another card or take a small loan just to add a new kind of account? In practice, the shortcut often costs more than it brings. Below we look at how scoring models treat account types, why new applications can work against you, and what matters more when your history is still short.
How scoring models look at account types
The Consumer Financial Protection Bureau lists the factors that credit scoring models typically consider in its explainer What is a credit score?. They include your bill-paying history, your current unpaid debt, and the number and type of loan accounts you have. Scoring models also consider how long those accounts have been open, how much of your available credit you use, and your new applications for credit. Finally, they look at whether a debt has gone to collection, a foreclosure, or a bankruptcy, and how long ago.
Account type is one item on that list, not the whole score. Our own FICO Score breakdown shows credit mix as a 10% share, next to factors that carry far more weight.
Why a car loan and a credit card count differently
Scoring systems do not treat every account the same way. The Federal Trade Commission notes in its guide to credit scores that some scoring systems weigh account types differently. Certain debt-consolidation loans, for example, may count against you, while a mortgage or an auto loan may not.
The same guide notes a second point. Having existing accounts can help your score, but having too many credit card accounts may lower it. So a car loan and a credit card on the same report are not interchangeable. Each is judged partly by its type and partly by how you handle it. A card paid on time with a low balance and an auto loan paid as agreed send a positive signal because the payments are steady, not because the two account types are different.
Why opening accounts just for variety can backfire
Every application leaves a trace. According to the FTC, each application appears as an inquiry on your credit report, and applying for many new accounts in a short period can hurt your score.
The CFPB makes a similar point in Understand your credit score. Opening accounts often and moving balances between them can hurt your score. Applying for a lot of credit in a short period may also suggest that your financial situation has gotten worse. A new account opened only for variety can also lower the average age of your accounts, and the length of time accounts have been open is a factor of its own.
Put together, the trade-off is uneven. The possible benefit of a broader mix is limited, while the cost of new inquiries and younger accounts shows up right away.
What matters more when your credit history is short
A short credit history is common for younger borrowers and for people who have just started using credit. The FTC says a short history can lower a score, but on-time payments and low balances can offset that effect.
The CFPB adds that a long credit history helps, because scores reflect your experience with credit over time. Time is the one factor no new account can speed up. That is why the accounts you already have matter most at this stage. Paying every bill on time and keeping card balances low builds the record that scoring models look for. Having a car loan and a credit card can help only if you manage them well. An extra account that strains your budget can do the opposite.
Inquiries that do not count against you
Not every look at your credit report counts as an application. The FTC explains that some inquiries do not affect your score. These include inquiries from creditors who are monitoring an account you already have, and inquiries tied to prescreened credit offers. When you shop for a mortgage, several mortgage inquiries within a short period often count as one.
This is useful when you compare loan offers. Shopping for one mortgage within a short window is treated differently from applying for several unrelated cards in the same month.
How a mix builds up over time
According to the CFPB, scores improve when you open different types of accounts over time. The important words are “over time”. For most people, a mix grows as real needs come up: a credit card for everyday spending, a car loan when a vehicle is needed, and perhaps a mortgage later.
A mix that grows this way comes with a payment history behind each account. A mix assembled in a few months comes with several new inquiries and very little history. The first kind of mix gives scoring models more to work with.
This page is for general information only and is not financial advice. Credit scoring models differ, and how your score changes depends on your full credit history.